

In our first post and the white paper, we use the term “emerging manager” in a very intentional way. It is not shorthand for inexperience, novelty, or lower investment quality. It is a description of a manager’s position within institutional capital systems and the constraints that position creates.
This distinction is important because much of the disconnect and many of the misallocations we observe in venture portfolios stem from how loosely the term is used in practice. When definitions are imprecise, screening criteria become blunt instruments, and performance signals are often missed.
How “Emerging” Is Commonly Understood
In institutional contexts, emerging managers are frequently framed as a carve-out, a pilot allocation, or a temporary stage on the path toward becoming an established institutional manager. In other cases, the term is implicitly linked to representation or access goals, rather than to portfolio construction and risk-return dynamics.
These framings persist, but they are not especially helpful for understanding how venture capital performance actually emerges. They blur together questions of identity, access, and risk, obscuring what is structurally happening within portfolios.
Our research takes a different approach.
A Structural Definition of “Emerging”
Rather than defining emerging managers by who they are, we define them by how institutional systems interact with them.
In the data, a manager is classified as emerging when structural features of their fund or firm place them outside standard institutional screening pathways, regardless of underlying investment capability.
Specifically, a fund qualifies as emerging if it meets any one of the following conditions:
1. Scale constraints
The fund operates below institutional AUM thresholds, often under $100M, which limits eligibility for many LP mandates independent of performance.
2. Limited institutional track record
The manager is raising Fund I, II, or III, or has a verifiable track record that does not map cleanly to institutional diligence templates and benchmarking norms.
3. Organizational youth
The firm is relatively young, often under five years old, with evolving operational infrastructure despite established investment processes and governance.
4. Overlooked teams
The manager sits outside dominant institutional referral channels, consultant networks, or brand ecosystems, a dynamic that affects many women-led and otherwise under-recognized teams.
None of these characteristics indicates a lack of investment skill. Instead, they describe access constraints that shape capital allocation before performance is fully evaluated.
Why This Definition Changes the Conversation
When institutional screening processes treat these structural features as proxies for risk, they function less as safeguards and more as filters. In practice, many emerging managers are screened out long before their portfolio construction choices, risk discipline, or realized outcomes are assessed.
This matters because the data tells a different story once performance is examined. But the story also shifts depending on how you define “emerging” in the first place. Definition choice is not a methodological footnote. It is one of the most consequential decisions in this research because different definitions isolate different manager populations, and those populations perform differently.
In short, emerging status is not a signal of underperformance. It is often a signal of misalignment between institutional processes and how venture capital actually generates returns.
The chart below shows IRR differences between emerging and non-emerging managers across five distinct definitional frameworks applied to our sample of 2,471 U.S.-based venture capital funds from 2000 through 2024.
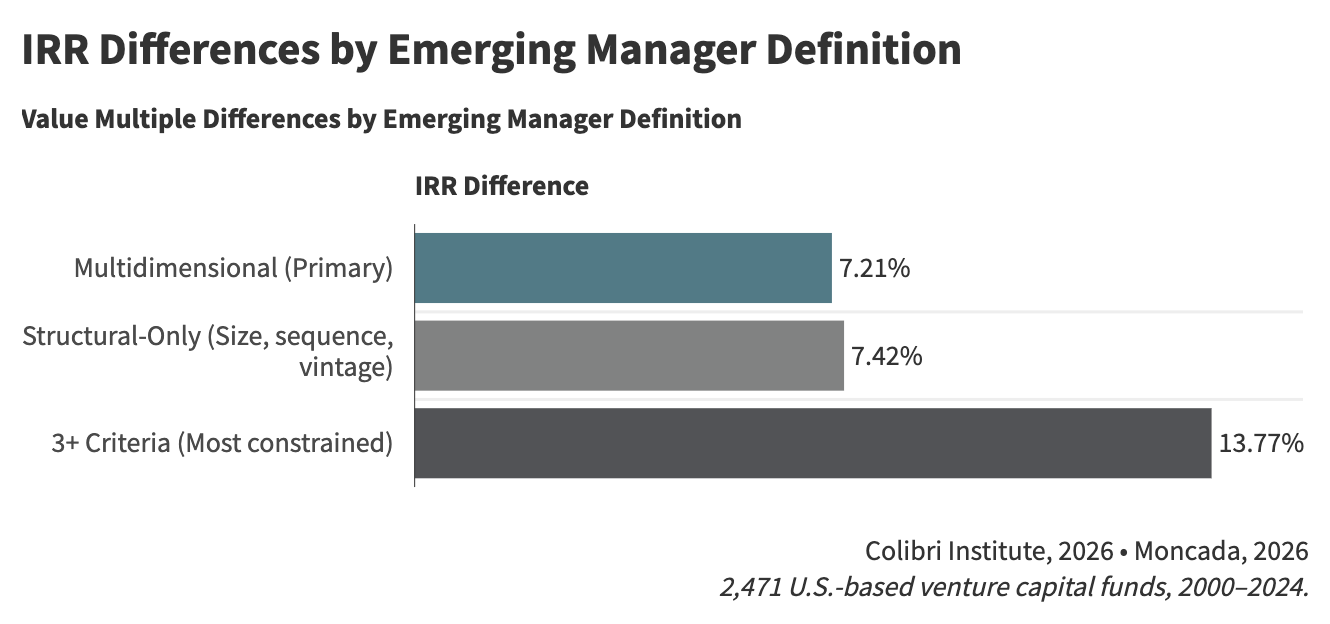
The spread across definitions is significant and worth sitting with. Using the multidimensional definition that anchors our primary analysis, emerging managers outperform by 7.21 percentage points on IRR. The structural-only definition, which isolates fund size, sequence, and vintage without accounting for team positioning, produces a similar result at 7.42 points. The most striking finding applies to managers who meet three or more criteria simultaneously, the most structurally constrained group in the sample. That cohort shows an IRR difference of 13.77 percentage points relative to non-emerging peers. Rather than compound constraints diluting the performance signal, they appear to amplify it.
The pattern holds, and in some cases intensifies, when you shift from return rates to value multiples.
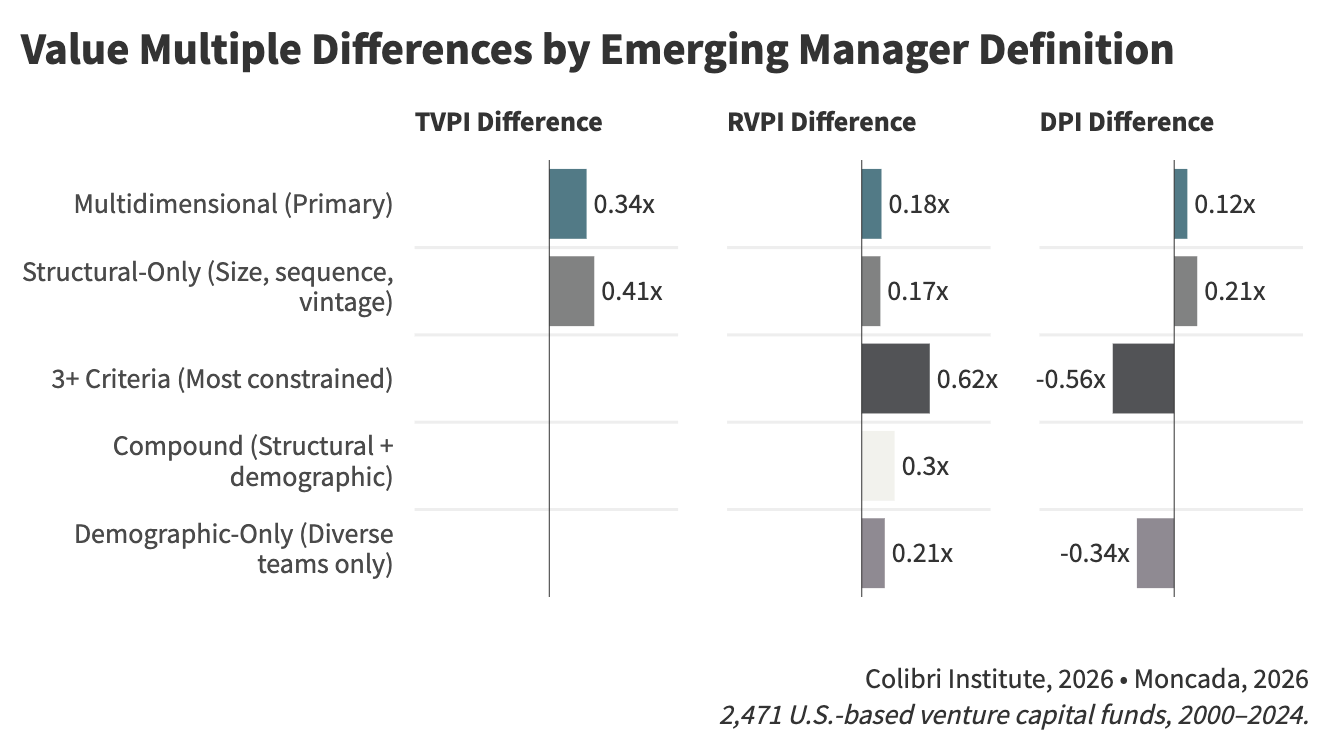
Under the multidimensional definition, emerging managers show a TVPI advantage of 0.34x and an RVPI advantage of 0.18x, with a more modest but positive DPI difference of 0.12x. The structural-only definition produces a slightly higher TVPI gap of 0.41x and a DPI gap of 0.21x. For the most constrained cohort, the RVPI advantage grows to 0.62x, though the DPI difference turns negative at -0.56x, a pattern consistent with managers who are earlier in fund maturation and carrying higher unrealized value relative to distributed returns.
When we require funds to meet both structural and demographic criteria simultaneously, the compound definition produces a different pattern: IRR differences narrow and become less consistent, but unrealized value remains meaningfully elevated at 0.30x. One interpretation from the paper is that funds facing both resource scarcity and demographic exclusion maintain strong portfolio quality, even when the path to exit and liquidity is more frictional.
Two things are worth noting in the 3+ criteria finding before moving on. First, a negative DPI does not indicate underperformance. It indicates where a fund sits in its lifecycle and how its value is distributed between realized and unrealized positions. Second, the demographic-only definition, which classifies managers based on team composition alone without reference to structural constraints, produces a considerably weaker and more mixed signal. The RVPI difference of 0.21x is positive, but the DPI difference of -0.34x is meaningfully negative, and TVPI data is not available for that cohort. This is not a knock on demographic considerations. It is evidence that demographics alone are an incomplete and sometimes misleading lens for understanding venture performance dynamics, a point the paper addresses directly.
Taken together, the data reinforce a central finding from Why Emerging Venture Capital Managers Matter: emerging status, when defined structurally, is not a signal of underperformance. It is often a signal of misalignment between institutional processes and how venture capital actually generates returns. And the more structurally constrained the manager, the wider that gap appears to be.
Emerging Does Not Mean Fragile
A common assumption in venture allocation is that smaller or newer funds are inherently riskier- our findings do not support that view.
Operational risk is driven by governance quality, financial controls, team dynamics, and the coherence of portfolio construction decisions across the fund lifecycle. Fund size alone is a poor proxy for these factors. In many cases, emerging managers exhibit greater discipline precisely because constraints force clearer trade-offs earlier.
When institutions equate size with safety, they risk overlooking managers whose structures are well-suited to a venture’s power-law dynamics and misclassifying access constraints as risk exposure.
Why We Start With Definitions
We begin the research agenda by redefining what “emerging” actually means because downstream decisions depend on it. Portfolio construction, screening criteria, program design, and pacing assumptions all rest on how managers are categorized at the outset.
If emerging managers are understood primarily as structurally excluded rather than fundamentally weaker, then the implications are significant. Screening systems need to evolve, portfolio construction frameworks need to adapt, and emerging manager programs need to be treated as core components of venture exposure rather than peripheral experiments.
That shift challenges long-standing institutional habits. It also clarifies where the performance opportunity lives.
In the next posts, we will examine how these structural definitions interact with check size discipline, portfolio breadth, and screening rules to produce the performance outcomes observed in the data.
For now, the central takeaway is this: emerging managers are not a category of exception. They are a category that reveals where institutional capital systems are misaligned with venture capital’s underlying economics.
Risk, AUM, and a Persistent Category Error
One of the most persistent assumptions in institutional venture allocation is that larger funds are inherently safer and smaller funds are inherently riskier. In practice, this conflates fund size with enterprise risk.
Enterprise risk in venture capital is driven by operational fundamentals: governance quality, financial controls, team alignment, key-person concentration, and the coherence of systems supporting the investment platform. These factors vary widely within both large and small funds.
As the framework above illustrates, high and low enterprise risk exists at every level of AUM. There are well-run emerging funds with clean documentation, disciplined financial management, and professional operations. There are also established platforms with weak governance, operational drift, and concentrated key-person risk. Fund size alone does not distinguish between the two.
When institutional screening processes use AUM thresholds as a proxy for safety, they introduce a structural blind spot. Smaller funds with low enterprise risk are excluded, while larger platforms with material operational vulnerabilities may pass initial screens without deeper scrutiny.
The implication is not that all emerging managers are low risk, or that all established managers are fragile. It is that risk must be evaluated directly, based on operational realities, rather than inferred from scale. Treating AUM as a substitute for enterprise risk assessment systematically misclassifies managers and distorts portfolio construction decisions.
Colibrí Institute publishes open research to improve how capital is allocated. If this was useful, consider sharing.
What’s Next
We’re committed to producing open-access research that improves how venture capital functions—and how it intersects with technology, policy, and economic opportunity.
Coming soon:
Deeper dives into specific findings from our first white paper
Research at the intersection of capital systems, technology policy, and institutional decision-making
Convenings that bring together allocators, managers, policymakers, and researchers
If there are questions you’d like us to explore, reply to this email or leave a comment. We’re building this in public, and your input shapes what we work on.
Support Our Work
Colibrí Institute is a nonprofit. Our research is open-access by design because we believe better data should be available to the entire ecosystem, not just those who can pay for it.
We partner with mission-aligned institutions to fund independent research on venture capital, technology, and policy.
If your organization is interested in supporting this work, reach out to us at hello@colibri.institute
Follow along:
→ Mariela on LinkedIn
→ Itzel on LinkedIn
→ Colibrí Institute on LinkedIn
— Mariela & Itzel